How Much is Auto Insurance in Massachusetts: A Comprehensive Guide to Costs and Coverage

Ever wondered how much auto insurance in Massachusetts will set you back? You’re not alone. Navigating the world of auto insurance can feel like trying to read a map in a foreign language. That’s why we’re here to break it all down for you—no need to dig through tons of pages or get lost in legalese. We’ve got you covered!
In this guide, we’re diving deep into the nitty-gritty of Massachusetts auto insurance. From mandatory requirements to factors affecting your premiums, average rates, and tips to cut costs—we’re spilling all the secrets. So buckle up and get ready to become an auto insurance know-it-all!
Overview of Auto Insurance Requirements in Massachusetts

Did you know that failing to meet Massachusetts’ auto insurance requirements can cost you more than $5,000? Let’s dive into what you absolutely need to know about auto insurance in the Bay State.
Massachusetts has some of the most stringent auto insurance laws in the country. And, if you’re driving here, you’d better be insured to the teeth.
Mandatory Auto Insurance Coverages
To legally drive in Massachusetts, you must have four types of coverage. First, there’s the Bodily Injury to Others, which covers at least $20,000 per person and $40,000 per accident. Next, you must have Personal Injury Protection (PIP) of $8,000. Then, there’s the Bodily Injury Caused by Uninsured Auto with minimums of $20,000 per person and $40,000 per accident. Finally, the Property Damage coverage must be at least $5,000.
Optional Coverages
But don’t just stop at the basics. Consider adding Comprehensive and Collision Coverage to protect your vehicle from theft and accidents. You might also want Medical Payments for extra medical expense coverage. And let’s not forget Rental Reimbursement if your car is in the shop. Each optional coverage can give you peace of mind when the unexpected happens.
Penalties for Driving Without Insurance
Here’s the deal: Driving uninsured in Massachusetts is a massive no-no. If caught, you face fines up to $5,000, license suspension, and a year in prison. Plus, you’ll have a hefty hike in insurance premiums after reinstatement. So, it’s not worth the risk. Always ensure your coverage is up-to-date.
Pro Tip: Always keep a copy of your insurance card in your glove box. You never know when you’ll need it.
Factors Influencing Auto Insurance Costs in Massachusetts
Ever wondered why your car insurance bill is sky-high even with a clean driving record? It’s all about the factors that insurers weigh when setting rates, and in Massachusetts, these can vary greatly.
Let’s dive into what really moves the needle on those premiums, from your age and ride to where you hang your hat.
Impact of Age, Driving History, and Vehicle Type
Your age is a biggie. Insurers love data, and statistics show younger drivers are more prone to accidents. That means higher premiums for the under-25 crowd. On the flip side, being a seasoned driver with a squeaky-clean record can earn you some sweet rate reductions.
Then there’s your wheels. Drive a flashy sports car? Expect your insurance costs to rev up. Sedans and family-friendly SUVs, however, often come with lower premiums. Why? They’re statistically less likely to be involved in costly crashes.
Pro Tip: If your driving history is blemished, consider a defensive driving course. It can often snag you a discount and boost your safety skills.
The Role of Location on Insurance Rates
Believe it or not, your zip code is a major player in determining your rates. Urban areas like Boston see higher premiums due to increased traffic and, you guessed it, more accidents and thefts. Meanwhile, living in the peaceful suburbs might just save you some cash.
But here is the deal: even within the same city, rates can fluctuate based on local crime statistics and accident data. It’s like real estate—location, location, location.
Discounts and Incentives Offered by Insurers
Who doesn’t love a good discount? Many insurers in Massachusetts roll out the red carpet with incentives. Good student discounts are a thing, rewarding young drivers hitting the books with reduced rates.
Multi-policy discounts can also unlock savings. If you’ve got your home and auto covered under the same insurer, they might just throw you a bone with a price cut. And let’s not forget anti-theft devices—if your car is equipped, you might just shave some dollars off your bill.
Average Auto Insurance Rates in Massachusetts
Did you know that Massachusetts drivers pay some of the highest auto insurance rates in the entire United States? It’s true. In fact, the average annual premium here is almost $1,460, which beats the national average of $1,070 by a long shot.
But there’s more to it than just that lump sum. Auto insurance rates can vary greatly depending on the type of vehicle you drive and where you live in the state. Let’s break down these numbers and see what they mean for you.
Average Insurance Costs for Different Vehicle Categories
When it comes to insuring your vehicle, the type matters a lot. For instance, insuring a luxury car is a whole different ball game compared to a modest sedan. In Massachusetts, luxury vehicles can see premiums surpassing $2,500 annually, while economy cars hover around $1,200.
Here’s the deal: if you’re driving an SUV, expect to pay slightly above average, at around $1,600. That’s because SUVs are often deemed safer, but also cost more to repair if you get into an accident.
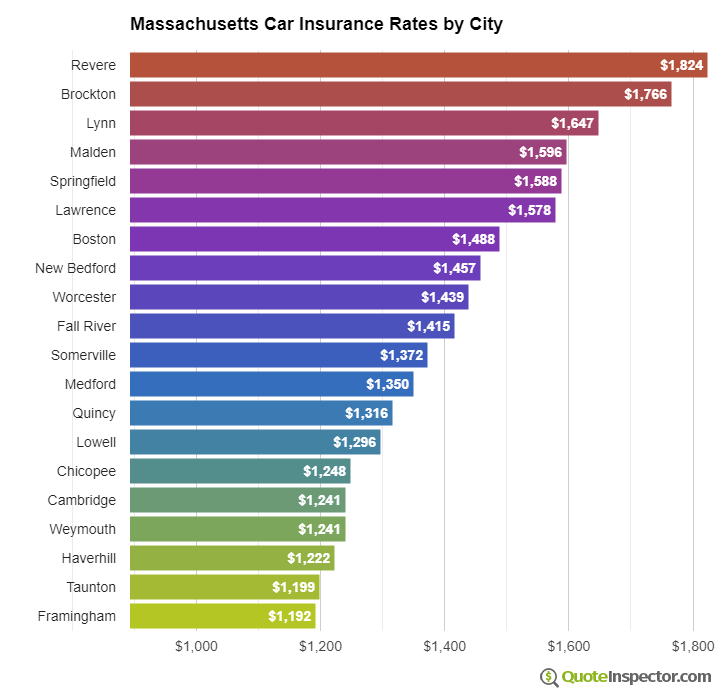
Premium Rates Across Massachusetts Cities
Your zip code can also add an extra twist to your insurance rate. Let’s dive into how much you might pay depending on where you park your car every night:
| City | Average Annual Premium |
|---|---|
| Boston | $1,800 |
| Worcester | $1,550 |
| Springfield | $1,520 |
| Cape Cod | $1,300 |
Surprisingly, living in Boston could cost you almost $500 more annually than if you were in Cape Cod. But you might already be guessing that urban areas generally mean higher premiums due to increased traffic and theft risk.
Comparing Massachusetts Rates to National Averages
So, how does Massachusetts stack up against the rest of the country? Well, the Bay State is notorious for higher rates. Remember when I mentioned that the national average is about $1,070? Massachusetts drivers are paying nearly 40% more on average!
If you’re feeling the pinch, you’re not alone. But don’t worry, there are always ways to bring costs down.
Pro Tip: Consider bundling your auto insurance with other policies like home insurance. It can lead to significant discounts.
Tips to Reduce Auto Insurance Costs
Looking to save some serious cash on your auto insurance? You’re not alone. Many drivers in Massachusetts are paying more than they should. But you can change that.
Here’s the deal: with a few smart moves, you can slash your premium costs significantly. Let’s dive into some actionable tips that could lighten your financial load.
Smart Strategies to Cut Insurance Premiums
Want to lower your insurance bill? Start by driving safely. A clean driving record is like a golden ticket to lower rates. Insurers love it when you’re risk-free on the road.
- Increase Your Deductible: Boosting that upfront cost can reduce your monthly payments.
- Shop Around: Don’t settle for the first quote. Compare prices from at least three different insurers.
- Ask for Discounts: Inquire about any available discounts like those for good students or low-mileage drivers.
Bundle Policies for Bigger Savings
Bundling isn’t just for phone plans. By combining your auto insurance with another policy, like home insurance, you can snag a discount. Insurers love loyalty, and they’ll often reward you for it.
Pro Tip: Not all bundles are created equal. Make sure the bundled cost is actually lower than buying policies separately.
Maintain a Good Credit Score
Did you know that your credit score can affect your auto insurance rate? It’s true. Insurers see a strong credit score as an indicator of responsible behavior, which means you’re less likely to file claims.
Avoid late payments and keep your credit utilization low. By doing so, you could see a nice dip in your insurance premiums. Here’s a quick comparison of how credit scores can impact your rates:
| Credit Score Range | Potential Rate Impact |
|---|---|
| Excellent (750+) | Lowest Rates |
| Good (700-749) | Moderate Savings |
| Fair (650-699) | Average Rates |
| Poor (600-649) | Higher Rates |
| Very Poor (<600) | Highest Rates |
Major Auto Insurance Providers in Massachusetts
Ever wonder which auto insurance companies dominate the Massachusetts market? Choosing the right insurer can save you hundreds of dollars annually, yet many drivers stick to the first quote they get.
Massachusetts is home to several big-name insurance providers. Each offers unique benefits, but some come with unavoidable downsides. Let’s dive into the details of the major players and see who comes out on top.
Top Auto Insurance Companies and Their Offerings
When it comes to securing coverage in Massachusetts, a few companies stand out. Liberty Mutual is one of the most recognized names, offering a variety of coverage options and excellent customer service. However, their premiums tend to be on the higher side. Then there’s Geico, known for their competitive rates and easy-to-use online platform, but their customer service reviews are a mixed bag.
Progressive offers innovative tools like their Name Your Price tool, which helps you find coverage that fits your budget. But, their discounts are not always the best. Allstate provides comprehensive coverage options and rewards safe drivers through their Drivewise program. On the downside, they are often criticized for their claims process.
Comparison of Services and Pricing Among Top Insurers
Let’s break down the offerings of the major insurers in Massachusetts to see how they compare.
| Provider | Strengths | Weaknesses | Average Premium |
|---|---|---|---|
| Liberty Mutual | Variety of coverage options, strong customer service | Higher premiums | $1,350 |
| Geico | Competitive rates, user-friendly online platform | Mixed customer service reviews | $1,100 |
| Progressive | Innovative tools, flexible pricing | Lacks strong discounts | $1,200 |
| Allstate | Comprehensive options, rewards for safe driving | Average claims process | $1,300 |
Pro Tip: Don’t just look at the price. Consider the quality of service and available discounts, as these can greatly affect your overall experience.
Ultimately, each insurer offers something unique. The key is to weigh the pros and cons according to what matters most to you—be it cost, coverage options, or customer service quality. Make sure to compare quotes and policy details to find the best fit for your needs.
Legal and Consumer Protection Aspects
Did you know that Massachusetts is one of the most strict states when it comes to auto insurance laws? If you’re driving in Massachusetts, there are several legal aspects you need to be aware of to stay compliant and protect yourself.
Massachusetts enforces strict auto insurance requirements to ensure that all drivers have adequate coverage. This includes mandatory minimum coverage levels for bodily injury, property damage, and personal injury protection. But the reality is, not knowing these laws can get you in serious legal trouble.
Laws Governing Auto Insurance in Massachusetts
In Massachusetts, auto insurance is not just a suggestion; it’s the law. The state requires you to have a minimum of $20,000 per person and $40,000 per accident for bodily injury coverage. Additionally, you must have $5,000 for property damage and Personal Injury Protection (PIP) covering up to $8,000 per person, whether you’re at fault or not.
Not having this coverage? You’re risking fines, license suspension, and even vehicle impoundment. Here’s the deal: Massachusetts operates under a “no-fault” system, which means your own insurance covers your losses regardless of who caused the accident.
Consumer Rights and Resources for Insurance Disputes
If you feel your rights as a consumer have been violated, you’ve got options. Massachusetts law provides you the right to a fair claims process, and if you disagree with an insurance company’s decision, you can file a complaint with the state.
Pro Tip:
Always document every correspondence with your insurance provider. This can be crucial if you need to escalate the issue.
Massachusetts offers resources like the Consumer Services Division where you can ask questions, file complaints, and seek mediation services. This division is part of the Division of Insurance, ensuring you get a fair shake.
Contact Information for State Insurance Regulatory Bodies
Need to get in touch with the state regulatory body? Here’s how you can reach them:
- Division of Insurance: Call them at (617) 521-7794.
- Consumer Services Division: Dial (877) 563-4467, or email at doicse@state.ma.us.
These offices are your go-to resource for any insurance-related concerns or disputes. They can provide guidance, help mediate disputes, and ensure that your consumer rights are protected.
Final Summary
So there you have it—everything you need to know about auto insurance in Massachusetts. Whether you’re looking to save a few bucks or find the best provider, understanding these key points can make all the difference. Remember, knowledge is power, and with the right information, you’ll be cruising confidently on the roads of Massachusetts with the best coverage possible.
FAQ Section
What are the mandatory auto insurance coverages in Massachusetts?
Massachusetts requires drivers to have Bodily Injury to Others, Personal Injury Protection (PIP), Bodily Injury Caused by an Uninsured Auto, and Damage to Someone Else’s Property coverages.
How does age affect auto insurance premiums in Massachusetts?
Younger drivers often face higher premiums due to their lack of experience, while older, more experienced drivers typically benefit from lower rates.
Can my location in Massachusetts impact my insurance rates?
Yes, living in urban areas with higher traffic and accident rates can lead to higher insurance premiums compared to rural areas.
Are there discounts available for Massachusetts drivers?
Yes, insurers offer various discounts such as safe driver discounts, multi-policy discounts, and discounts for vehicles with safety features.
How do Massachusetts auto insurance rates compare to national averages?
Massachusetts auto insurance rates tend to be higher than the national average due to factors like dense population and higher repair costs.